Building your first money plan comes down to five moves, taken in order: know what comes in and what goes out, build a small cash cushion, pay down expensive debt, start saving for retirement, and protect what you have built. Each move makes the next one easier. Skip the order and the plan wobbles.
This is a personal plan, in the plain sense of the word. As Cambridge Dictionary defines it, personal means relating to a particular person, private. Your numbers are your numbers. The framework below works for almost anyone, but the amounts, dates, and tradeoffs belong to you alone.
One caution before the list: this article is information, not financial advice. It explains what the moves are and why the order matters. It does not tell you how much to put in each bucket, because that depends on figures no article can know.
Move one: write down what comes in and what goes out
Everything starts with a simple record of income and spending. No app is required at the start. A sheet of paper with two columns does the job: money in, money out.
List every source of income, after tax. Then list what you spend in a typical month. Rent or mortgage, food, transport, phone, insurance, debt payments, and the small stuff that adds up. Most people find the small stuff is the surprise.
What this means: the gap between the two columns is your planning space. A positive gap funds every later move. A negative gap tells you the real first problem is spending or income, not investing or saving strategy. Revisit the list monthly. A plan built once and never checked is not a plan.
Move two: build a starter cash cushion
A cash cushion is money set aside for surprises: a car repair, a medical bill, a gap between jobs. It sits in a savings account where you can reach it quickly, and where its job is boring reliability, not growth.
Why it comes before debt payoff and investing: without a cushion, every surprise goes on a credit card, and the surprise then costs you interest on top of the bill. The cushion breaks that cycle. It converts an emergency from a debt event into an inconvenience.
How much to hold is a personal decision, and common guidance ranges widely depending on how stable your income is. A steady salary supports a smaller cushion than freelance or commission income does. Start with whatever first target you can reach, then grow it. A partial cushion still stops the bleeding.
Move three: deal with expensive debt
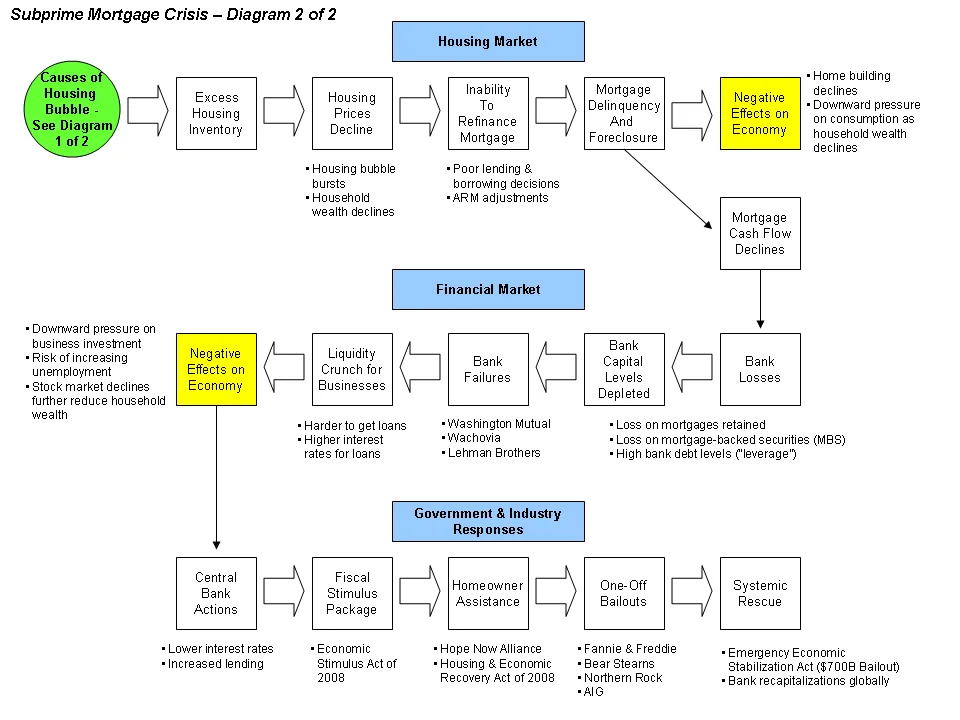
Not all debt deserves the same attention. Debt generally splits into two kinds: low-cost debt such as a fixed-rate student loan or mortgage, and high-cost debt such as credit card balances, where the interest rate is high and the balance can grow fast.
The practical rule most planners use: while you carry high-cost balances, paying them down is often the most reliable return available to you, because eliminating an interest charge is a guaranteed saving. There is no equivalent guarantee in investing. That is why this move sits ahead of the retirement move for most people, though employer retirement matches can change the calculation.
What this means in practice: list your balances with their interest rates. Attack the highest rate first while paying minimums on the rest, or clear the smallest balance first if momentum helps you stick with it. Both methods work. The one you finish is the better one. If your own situation involves a business, the same discipline applies on the company side, and our guide to When Refinancing Business Debt Actually Pays covers when restructuring replaces payoff.
Move four: start retirement saving, even if small
Retirement saving works through time more than through size. Money invested early has more years to compound, which is why a modest amount started young can outperform a larger amount started late. The exact math depends on returns nobody can promise, so treat any projection with care.
If your employer offers a retirement plan with a match, the match is the first place your savings go, because it is added money you cannot get any other way. If you are self-employed, the structure differs; our comparison of the SEP-IRA or Solo 401(k): The Self-Employed Retirement Math walks through the options.
What this means: automate the contribution. Money that moves on payday, before you see it, is money you never argue with yourself about. Raise the amount whenever income rises. Consistency, not cleverness, does the work here.
Move five: protect what you have built
The last move is defensive. Insurance, basic estate documents, and account hygiene all protect the plan you just built.
- Insurance. Health coverage comes first for most households, then coverage that replaces your income if you cannot work. The right amount depends on who depends on you.
- Basic documents. Even a simple will, and named beneficiaries on retirement accounts, prevent confusion later. Beneficiary designations usually override the will, so keep them current after life changes.
- Account hygiene. Separate your emergency fund from your spending account. Review statements monthly. Watch for charges you did not authorize.
For readers who also run a business, protection has an extra layer: the line between personal and business finances. Our piece on Personal Guarantees on Business Debt: What You're Really Signing explains how a business loan can reach personal assets, and How to Build Business Credit Without Personal Guarantees explains how to keep the two apart.
Our analysis: why the order matters more than the amounts
Beginners often ask which move matters most. Our reading of how these plans succeed and fail is that sequence beats size. A person with a cushion does not borrow at high rates when the car fails. A person without expensive debt has more cash flow to save. A person saving automatically does not depend on monthly willpower. Each move removes a failure mode for the next one.
The reverse also holds. A large investment account with no cash cushion is fragile, because the first surprise forces a sale, possibly at a bad time. A aggressive debt payoff with no cushion can loop straight back into new borrowing. The order is the plan.
For the underlying concepts, our explainer Finance 101: The Core Concepts Every Owner Should Know covers the vocabulary, and How to Use a Finance Calculator Like a Pro shows how to run the numbers yourself. For broader coverage of money topics, see our finance section.
What remains unknown is personal: your income stability, your rates, your dependents. Those facts decide the amounts. The five moves decide the shape. Fill in your numbers, take the moves in order, and review the plan once a month. That is the whole method.